
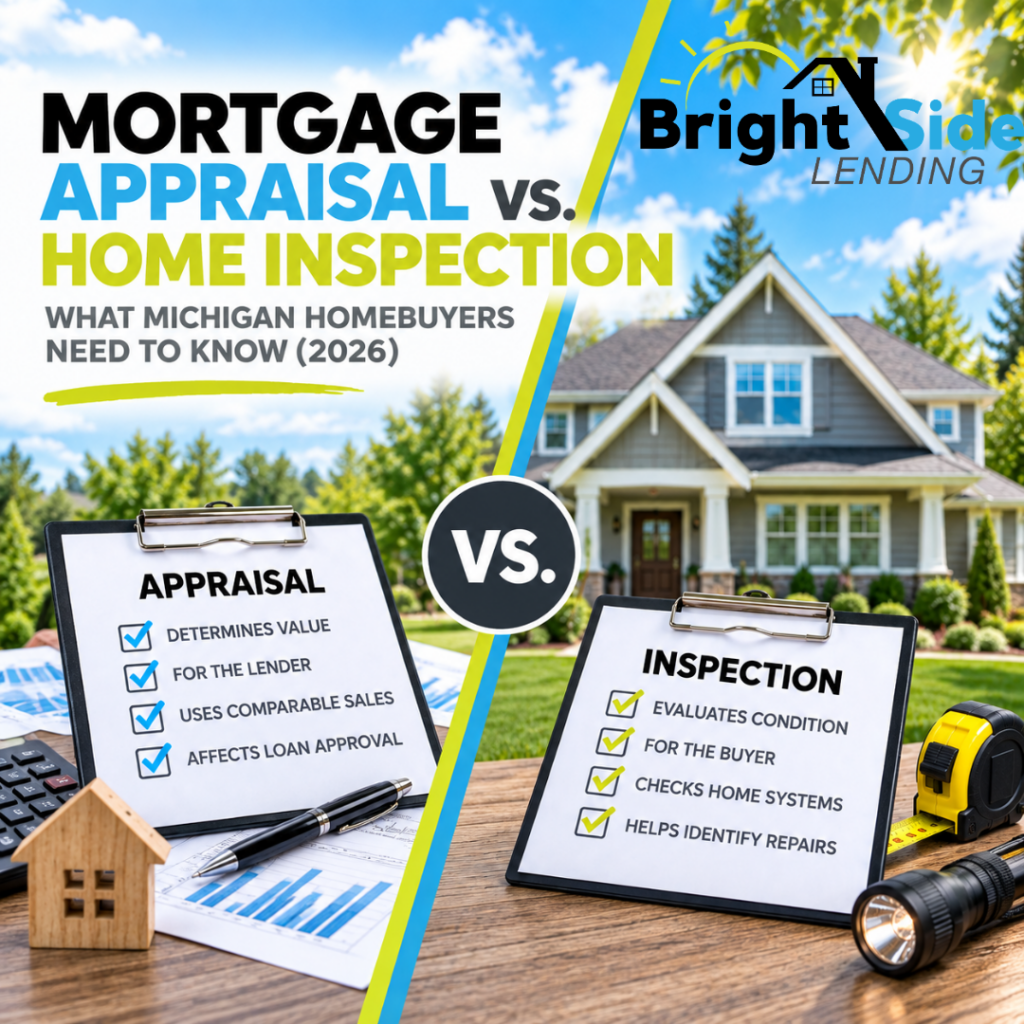
Mortgage Appraisal vs. Home Inspection: What’s the Difference for Michigan Homebuyers? (2026)
You found the house.
Your offer was accepted, the mortgage process is moving forward, and now two words start getting thrown around:
Appraisal. Inspection.
If you’re buying your first home, it would be completely reasonable to assume they’re basically two versions of the same thing.
They’re not.
A home appraisal and a home inspection serve very different purposes during a real estate transaction.
An appraisal primarily helps determine the property’s value for mortgage purposes and whether the property meets applicable lender and loan-program requirements.
A home inspection is primarily designed to help you, the buyer, understand the physical condition of the house you’re considering purchasing.
And one of the biggest misconceptions I hear from homebuyers is some version of:
“The house passed the appraisal, so everything must be okay with it.”
Not necessarily.
A house can appraise for the purchase price and still have a furnace that’s nearing the end of its life, water in the basement, electrical concerns, plumbing problems or other expensive issues that an appraisal was never designed to uncover.
The opposite can happen too.
A home inspection could reveal relatively few concerns, yet the appraisal could still come in below the agreed-upon purchase price.
Understanding the difference between the two can save Michigan homebuyers a lot of confusion—and potentially a lot of money.
Appraisal vs. Home Inspection: The Quick Answer
Here’s the easiest way to think about it:
The appraisal asks:
What is this property worth, and does it satisfy applicable requirements for the mortgage?
The home inspection asks:
What condition is this house actually in?
Those are very different questions.
Here’s a quick comparison:
| Home Appraisal | Home Inspection | |
|---|---|---|
| Main purpose | Determine property value and address applicable lender/program requirements | Evaluate the home’s physical condition |
| Primarily for | Mortgage/lending process | Buyer |
| Determines market value | Yes | No |
| Detailed examination of home systems | No | Yes |
| May affect mortgage approval | Yes | Usually not directly |
| Looks for defects | Certain observable/property-related issues may be noted | Yes, this is a primary purpose |
| Required for most mortgages | Usually | Generally no |
| Can buyer attend? | Usually not necessary | Often yes |
| Replaces the other? | No | No |
That last row is the important one.
An appraisal does not replace a home inspection.
And a home inspection does not replace an appraisal when an appraisal is required for the mortgage.
What Is a Home Appraisal?
A home appraisal is an independent professional opinion of a property’s value.
When you’re financing a home, the lender needs to know that the property supporting the mortgage is reasonably worth what everyone says it’s worth.
Think about it from the lending side.
Suppose you’re buying a house for $400,000 and borrowing $380,000.
If the property is actually worth only $325,000, that’s a major problem.
The lender isn’t simply evaluating your income, credit and assets.
The property itself is part of the mortgage transaction.
That’s why the appraisal becomes an important part of mortgage underwriting.
The appraiser typically considers characteristics such as:
- Location
- Property size
- Above-grade living area
- Number of bedrooms and bathrooms
- Overall condition and quality
- Lot characteristics
- Improvements and amenities
- Recent comparable sales
- Market conditions
- Other factors affecting marketability and value
The appraiser then develops an opinion of the property’s market value.
That value can have a major impact on the mortgage.
Who Does the Appraiser Work For?
This is another common source of confusion.
The buyer generally pays for the appraisal as part of the mortgage process, but that doesn’t mean the appraiser works for the buyer in the same way a home inspector does.
The appraisal is being obtained as part of the lending process.
The appraiser is expected to provide an independent opinion of value, not to make the deal work for the buyer, seller, real estate agent or mortgage company.
That’s important.
If the purchase agreement says $425,000, the appraiser isn’t supposed to simply find a way to justify $425,000.
Likewise, if everyone involved desperately wants the transaction to close, that doesn’t change what the property is worth in the appraiser’s professional opinion.
What Is a Home Inspection?
A home inspection is different.
The home inspector’s job is generally to evaluate the property’s physical condition and identify observable issues that a buyer should know about.
Depending on the property and scope of the inspection, the inspector may evaluate things such as:
- Roof
- Foundation
- Basement or crawlspace
- Electrical system
- Plumbing
- Heating and cooling systems
- Attic
- Insulation and ventilation
- Windows and doors
- Exterior
- Interior
- Appliances
- Drainage
- Signs of moisture intrusion
- Other visible components of the home
The goal isn’t to determine what the house is worth.
It’s to help the buyer understand what they’re buying.
That distinction is enormous.
The Appraiser Is Not Your Home Inspector
Let’s use a simple example.
You agree to purchase a home for $350,000.
The appraiser visits the property, analyzes comparable sales and determines that the home has a market value of $355,000.
Great.
The appraisal supports the purchase price.
Does that mean the house has no problems?
Absolutely not.
Your home inspector might discover:
- A furnace that’s 25 years old
- Evidence of previous basement water intrusion
- Improper electrical wiring
- A leaking plumbing connection
- Deteriorated roof flashing
- Poor attic ventilation
- A malfunctioning dishwasher
- A cracked window
- Evidence suggesting further evaluation by a specialist
The house could still be worth $355,000.
Value and condition aren’t the same question.
An appraiser isn’t performing the same detailed systems evaluation that a home inspector performs.
That’s why hearing “the appraisal was good” shouldn’t be interpreted as “the house has been thoroughly inspected and everything works.”
And the Home Inspector Is Not Your Appraiser
The reverse is equally important.
Suppose your inspector spends several hours evaluating the home and comes back with a relatively clean report.
The roof looks good.
The furnace is functioning.
The electrical system doesn’t reveal major visible concerns.
The basement is dry.
Excellent.
That still doesn’t tell us whether the home is worth the $450,000 purchase price.
The inspector isn’t analyzing comparable home sales to establish the property’s market value for the mortgage.
The appraisal could still come back at $425,000.
Now we have a completely different problem.
The house may be in fantastic condition.
It just may not support the price you’ve agreed to pay.
Why Does the Lender Care About the Appraised Value?
Because mortgage lending is partly based on loan-to-value, commonly called LTV.
Let’s say you’re buying a Michigan home for:
Purchase price: $400,000
You’re planning a 5% down payment:
Down payment: $20,000
That would normally produce a:
Loan amount: $380,000
But now imagine the appraisal comes back at:
$375,000
For mortgage qualification purposes, we generally can’t simply pretend the property is worth $400,000 because that’s what the purchase agreement says.
The lower appraised value can change the financing calculation.
And that’s where buyers can suddenly find themselves facing an appraisal gap.
We’ll get much deeper into appraisal gaps later in this guide because there are several possible ways to deal with one.
What Is an Appraisal Gap?
An appraisal gap occurs when the appraised value comes in below the agreed-upon purchase price.
For example:
Purchase price: $400,000
Appraised value: $385,000
Appraisal gap: $15,000
That doesn’t automatically mean the transaction is dead.
Depending on the purchase agreement, mortgage program and negotiations between the buyer and seller, there may be several possibilities.
The seller could reduce the price.
The buyer could potentially bring additional funds.
The parties could meet somewhere in the middle.
There may be an appraisal reconsideration process when appropriate.
Or the transaction could potentially fall apart depending on the contract and circumstances.
This is why the appraisal isn’t simply another box to check on the way to closing.
It can materially affect the financing.
Does an Appraisal Tell You Whether a House Is Safe?
Not in the same way a home inspection is intended to evaluate property condition.
An appraiser may observe and report certain conditions that affect value, marketability or eligibility under the applicable mortgage program.
But that doesn’t turn the appraisal into a comprehensive safety inspection.
For example, an appraiser may identify an obvious property issue.
That doesn’t mean the appraiser has:
- Tested every electrical outlet
- Evaluated the inside of the sewer line
- Performed a detailed furnace inspection
- Diagnosed the source of basement moisture
- Evaluated every plumbing connection
- Determined the remaining life of the roof
- Conducted specialized environmental testing
Those are different scopes of work.
This distinction becomes especially important with FHA and VA financing, because those programs have property requirements that sometimes lead buyers to believe the appraisal is actually a home inspection.
It isn’t.
We’ll cover that in detail shortly.
Is a Home Inspection Required to Get a Mortgage?
Generally, a traditional home inspection isn’t required simply because you’re obtaining a mortgage.
That surprises some buyers.
The lender may require an appraisal.
The buyer generally decides whether to obtain a separate home inspection, subject to the terms of the purchase agreement and the circumstances of the transaction.
That doesn’t mean skipping the inspection is automatically a good idea.
It means the inspection serves a different purpose.
The lender is primarily making a lending decision.
You’re making a home-buying decision.
Those interests overlap, but they’re not identical.
Who Pays for the Appraisal and Home Inspection?
Typically, the buyer pays for both, although how and when those costs are paid can differ.
The appraisal is generally ordered through the mortgage process, and the appraisal charge should be disclosed as part of your mortgage costs.
If you’re trying to understand where appraisal charges and other lender-related costs appear, our guide on how to read a Loan Estimate and spot hidden fees explains the document buyers receive early in the mortgage process.
A home inspection is generally arranged separately by the buyer and is not the same thing as a lender-required appraisal fee.
This is also why buyers need to think about more than just their down payment when determining how much money they need to buy a home.
There can be costs incurred during the transaction before you ever reach the closing table.
Should You Get the Inspection Before the Appraisal?
Often, yes—but the exact timing depends on the transaction.
There is a practical reason many buyers want to complete the inspection early.
Suppose you spend money on an appraisal and then discover through the home inspection that the property has major problems and you no longer want to proceed, assuming your contract allows you to terminate.
You may have paid for an appraisal that you ultimately didn’t need.
On the other hand, mortgage timelines matter.
Waiting too long to order an appraisal can create delays later, particularly if you’re working with a short closing period.
This is where communication between the buyer, real estate agent and mortgage company becomes important.
We want to protect the buyer’s interests without unnecessarily slowing down the mortgage process.
What Happens After the Appraisal Is Ordered?
Once the appraisal is ordered, the appraiser typically gathers information about the property, completes the necessary property observation and analyzes relevant market data and comparable sales.
The completed appraisal is then delivered through the appropriate mortgage process for review.
From there, several things can happen.
The value supports the purchase price and there are no significant appraisal-related issues.
Great.
We keep moving.
The value comes in low.
Now we need to address the appraisal gap.
The appraiser identifies a condition that needs to be corrected or further evaluated.
Now we may have an appraisal-related repair or documentation issue.
Or the appraisal could contain information that requires additional underwriting review.
That’s why an appraisal can affect more than just the property’s value.
The Biggest Mistake: Treating “Appraised” as “Inspected”
If there’s one thing I want Michigan homebuyers to take from this first section, it’s this:
Do not use a successful appraisal as evidence that you don’t need to understand the condition of the house.
The appraisal and inspection are answering different questions.
The appraisal may tell us:
“The value supports the mortgage.”
The inspection may tell you:
“You’re probably going to need a roof in three years.”
Both pieces of information can be extremely important.
But they’re important for completely different reasons.
Are FHA and VA Appraisals the Same as Home Inspections?
No.
This is probably the biggest source of confusion surrounding appraisals and inspections.
You’ll often hear buyers, sellers and even people in the real estate industry say things like:
“FHA has a really strict inspection.”
or:
“I’m worried the house won’t pass the VA inspection.”
What they’re usually talking about is the FHA or VA appraisal.
FHA and VA appraisals can include property-condition requirements that aren’t necessarily evaluated the same way on every Conventional mortgage.
But they’re still appraisals.
They are not substitutes for a professional home inspection.
That’s an important distinction because a buyer could have a property satisfy FHA or VA appraisal requirements and still discover significant issues during a separate home inspection.
Why Do FHA and VA Care About Property Condition?
Remember that an appraisal has more than one potential function in the mortgage process.
Determining value is obviously a major one.
But certain mortgage programs also establish minimum property requirements or standards that the property needs to satisfy.
With FHA financing, the property generally needs to meet HUD requirements involving safety, security and soundness.
VA financing also has Minimum Property Requirements, commonly called MPRs.
That’s why an FHA or VA appraiser may identify certain property conditions that need to be addressed before the mortgage can close.
This is different from hiring an inspector whose primary job is to perform a detailed evaluation of the home’s condition for the buyer.
What Does an FHA Appraiser Look For?
An FHA appraisal includes an opinion of value, but the appraiser also observes the property for conditions relevant to FHA eligibility.
The appraiser isn’t performing a full home inspection.
However, certain visible conditions can create an issue.
Depending on the property, those could include things such as:
- Defective or deteriorated paint surfaces
- Safety hazards
- Certain electrical concerns
- Missing or inadequate required components
- Evidence of significant water intrusion
- Roof problems
- Structural concerns
- Inadequate access
- Issues involving utilities
- Certain health or safety concerns
- Other conditions affecting the property’s safety, security or soundness
The exact circumstances matter.
This doesn’t mean an FHA appraiser walks around with a giant checklist looking for every cosmetic flaw in the house.
And it definitely doesn’t mean an FHA-financed home needs to be perfect.
That’s another misconception worth clearing up.
Does an FHA House Have to Be in Perfect Condition?
Absolutely not.
FHA financing is used to purchase older homes every day.
A house doesn’t have to have:
- A brand-new kitchen
- New flooring
- Modern bathrooms
- New appliances
- Fresh paint everywhere
- A finished basement
- Perfect landscaping
An FHA appraisal isn’t a beauty contest.
An outdated kitchen can still be perfectly functional.
Old carpet isn’t automatically an FHA problem.
A bathroom decorated in 1987 may offend your eyes, but that’s different from the property failing to meet an FHA requirement.
The important distinction is generally between:
Cosmetic condition
and
conditions affecting safety, security, soundness or other FHA property requirements.
That’s why buyers shouldn’t automatically eliminate FHA financing simply because they’re considering an older home.
Does FHA Require Peeling Paint to Be Repaired?
Peeling or defective paint is one of the most famous FHA appraisal issues—and one of the most misunderstood.
The age of the home matters because of concerns involving lead-based paint.
For homes built before 1978, defective paint surfaces can create an FHA issue because of potential lead-based paint hazards.
That could include:
- Peeling paint
- Chipping paint
- Flaking paint
- Other defective painted surfaces
And it isn’t necessarily limited to the interior.
Exterior surfaces, garages, sheds and other applicable painted areas can matter.
If defective paint is identified and repairs are required, the loose or defective paint may need to be properly addressed before the loan can proceed.
This is one reason an experienced real estate agent and mortgage professional should recognize potential FHA property issues before everyone gets surprised by the appraisal.
What About Missing Handrails?
This is another one people hear constantly.
“FHA requires handrails everywhere.”
That’s too broad.
The real issue is whether a condition presents a safety concern under the applicable property requirements.
A staircase or elevated area presenting a legitimate fall hazard can potentially result in an appraisal condition.
But we shouldn’t reduce FHA property requirements to internet folklore like:
Three steps = handrail required.
Mortgage and appraisal requirements aren’t best handled through made-up universal rules.
The appraiser evaluates the property under the applicable standards and identifies conditions that require correction.
What About the Roof?
An appraiser isn’t performing the same roof inspection a qualified home inspector or roofing contractor might perform.
But obvious roof problems can matter.
For example, significant visible deterioration, active leakage or other conditions affecting the property’s soundness may create an issue.
That’s different from determining:
“This roof probably has four years of useful life left.”
A home inspector may provide much more information about the roof’s observable condition and recommend evaluation by a roofer when appropriate.
Again, we’re seeing the same theme:
Appraisal = mortgage eligibility and value.
Inspection = buyer’s understanding of condition.
Do the Utilities Have to Be On for an FHA Appraisal?
Utilities can become important because certain property systems may need to be operational or observable for the appraisal and mortgage requirements to be satisfied.
This sometimes creates problems with vacant or winterized properties.
Imagine buying a vacant Michigan home in February.
The property has been winterized.
Water is shut off.
Now the appraiser can’t observe certain systems under normal operating conditions.
Depending on the circumstances and applicable requirements, additional steps may be necessary.
This is one reason vacant properties can sometimes require more coordination than occupied homes.
What If the FHA Appraiser Finds a Problem?
An appraisal condition doesn’t necessarily mean the mortgage is denied.
It may simply mean the issue needs to be corrected before the loan can close.
For example, suppose the appraiser identifies a required repair.
The seller agrees to make the repair.
Once completed, the property may need to be reinspected or otherwise documented to confirm the condition has been corrected.
Then the mortgage process can continue.
The bigger issue is often:
Who is going to make the repair?
That’s where the mortgage and real estate transaction intersect.
The buyer generally doesn’t own the property yet.
The seller may or may not want to spend money making repairs.
The purchase agreement may address how certain situations are handled.
And if the parties can’t reach an agreement, the transaction can become more complicated.
Can the Buyer Pay for FHA-Required Repairs Before Closing?
This is a situation where I’d want everyone involved to be cautious.
A buyer generally doesn’t own the home before closing.
Spending substantial money repairing someone else’s property can create obvious risks if the transaction ultimately doesn’t close.
There can be situations where repairs are handled before closing, but the arrangement needs to make sense and should be coordinated with the appropriate parties.
Don’t simply show up at the seller’s house with a ladder and a can of paint because the appraisal mentioned peeling paint.
There may be contractual, liability and mortgage considerations that need to be addressed first.
What If the Seller Refuses to Make an FHA Repair?
Then we need to evaluate the options.
Depending on the issue, purchase agreement and circumstances, possibilities might include:
- Negotiating with the seller
- Determining whether another permitted repair arrangement exists
- Evaluating a different mortgage structure
- Considering renovation financing when appropriate
- Determining whether the transaction can continue at all
This is one area where an FHA 203(k) renovation loan can sometimes become relevant.
A property that isn’t eligible for a standard FHA mortgage in its current condition doesn’t necessarily mean the buyer has no FHA options.
Depending on the repairs and transaction, renovation financing may allow eligible improvements to be incorporated into the financing.
That’s a completely different mortgage structure, though, and needs to be planned accordingly.
What About Conventional Appraisals?
There’s another misconception on the opposite side:
“Conventional doesn’t care about condition.”
That’s not accurate either.
A Conventional appraisal isn’t simply:
House is worth $400,000. Done.
Property condition can still matter.
Significant defects affecting safety, soundness, structural integrity, marketability or the property’s suitability as collateral can potentially create issues on a Conventional mortgage too.
The difference is that FHA and VA have specific program requirements that can make certain property-condition issues more noticeable during the appraisal process.
You shouldn’t assume a severely distressed property will automatically work simply because you’re using Conventional financing.
What Does a VA Appraiser Look For?
VA appraisals also involve both value and property eligibility considerations.
VA’s Minimum Property Requirements are intended to help ensure the property meets applicable standards for the VA loan guaranty.
Depending on the property, issues can involve areas such as:
- Safe and adequate access
- Sanitary facilities
- Mechanical systems
- Roof condition
- Water supply
- Sewage disposal
- Structural concerns
- Certain safety hazards
- Other applicable Minimum Property Requirements
Again, this isn’t the same as a comprehensive home inspection.
A Veteran should not assume:
“The VA appraiser didn’t require any repairs, so I don’t need an inspection.”
Those are two different evaluations.
Is a VA Appraisal More Difficult Than a Conventional Appraisal?
Not necessarily “more difficult.”
It’s more accurate to say that the programs have different property requirements.
A well-maintained home may have no meaningful VA appraisal issues at all.
The problems tend to arise when a property has visible deficiencies that conflict with applicable VA requirements.
This is why blanket statements such as:
“Sellers don’t want VA buyers because VA appraisals are impossible.”
are misleading.
Plenty of homes finance successfully with VA loans every day.
The key is understanding the property and the program rather than treating VA financing as inherently problematic.
FHA Appraisal vs. FHA Home Inspection
Here’s the distinction worth remembering:
FHA Appraisal
Evaluates the property’s value and observes the property for applicable FHA requirements.
Home Inspection on an FHA Purchase
Provides the buyer with a much more detailed evaluation of the home’s physical condition.
You can—and often should—have both.
The fact that you’re using FHA financing doesn’t mean HUD has sent someone out to inspect the house on your behalf.
The appraisal serves the mortgage process.
The inspection serves a different purpose for the buyer.
VA Appraisal vs. Home Inspection
The same basic principle applies to VA.
VA Appraisal
Establishes an opinion of value and evaluates applicable VA Minimum Property Requirements.
Home Inspection
Provides the Veteran or other buyer with a more detailed understanding of the property’s physical condition.
One does not replace the other.
For eligible Veterans considering their financing options, understanding how VA home loans work in Michigan is important because VA financing offers significant benefits that go far beyond the appraisal process.
Can a House “Fail” an Appraisal?
People commonly say:
“The house failed the appraisal.”
That’s not always the best way to describe what happened.
There are several different appraisal-related outcomes that people lump together as a “failed appraisal.”
For example:
The value came in low.
That’s primarily a valuation issue.
Repairs are required.
The value may be perfectly fine, but a property condition needs to be corrected before the mortgage can proceed.
The property isn’t eligible in its current condition.
That’s potentially a larger property or loan-program issue.
The appraisal needs additional information.
Sometimes underwriting or appraisal review requires clarification or additional documentation.
Those are very different problems and may have very different solutions.
So when someone says:
“The appraisal failed,”
my next question is:
Why?
Can a Home Pass FHA Appraisal and Still Have Major Problems?
Yes.
This is exactly why the distinction between appraisal and inspection matters.
Imagine an FHA appraisal is completed and no repairs are required.
The home supports the purchase price.
Fantastic.
Then the buyer’s inspector identifies:
- Significant sewer-line deterioration
- An aging furnace
- Evidence of previous basement leakage
- Electrical concerns
- Poor attic ventilation
None of that automatically means the appraiser did something wrong.
The two professionals were performing different jobs.
A specialized sewer scope, for example, can uncover something that nobody could reasonably determine simply by observing the property during an appraisal.
That’s why buyers need to understand what each service does—and what it doesn’t do.
Can a Home Pass Inspection but Have FHA Appraisal Problems?
Absolutely.
Suppose the inspector tells you:
“Overall, this house is in good shape.”
But the FHA appraiser identifies defective paint on an applicable pre-1978 structure that needs to be corrected.
Those findings aren’t necessarily contradictory.
The inspector evaluated the property from the buyer’s condition perspective.
The appraiser evaluated it under FHA appraisal requirements.
Both can be correct.
Should Sellers Be Afraid of FHA or VA Offers?
Not simply because they’re FHA or VA.
A seller should evaluate the entire offer.
That includes things like:
- Purchase price
- Buyer qualification
- Financing
- Down payment
- Contingencies
- Closing timeline
- Property condition
- Strength of the buyer’s mortgage pre-approval
A strong FHA or VA buyer can be an excellent buyer.
And a weak Conventional buyer doesn’t magically become stronger because the word “Conventional” appears on the pre-approval letter.
This is one reason we’ve emphasized that pre-approval letters are not all the same and sellers judge them differently.
The strength of the transaction involves much more than the loan-program label.
What About a House That Needs Significant Repairs?
This is where the appraisal-versus-inspection conversation becomes even more important.
Suppose you find a house you love, but it needs:
- A new roof
- Significant electrical work
- Plumbing repairs
- Kitchen renovation
- Flooring
- Bathroom updates
- Other improvements
The home inspector can help identify the condition.
The appraisal can affect whether the property qualifies for the proposed mortgage in its current state.
And the mortgage program determines what financing options may be available.
A standard mortgage may work.
A renovation mortgage may make more sense.
Or the property may simply require too much work for the buyer’s goals.
This is why financing should be considered before making assumptions about a fixer-upper.
The Appraisal Isn’t Just About “Passing”
Instead of thinking:
“Will the house pass appraisal?”
I prefer buyers think about three separate questions:
1. Does the value support the transaction?
2. Does the property meet the applicable requirements for the mortgage program?
3. Am I personally comfortable with the property’s condition?
The appraisal helps answer the first two.
The inspection can help you answer the third.
And you really want answers to all three before you own the house.
What Happens If the Appraisal Comes in Low?
This is the part of the appraisal process that makes buyers nervous.
You’ve found the house.
Your offer was accepted.
You’ve completed the inspection.
You’re excited about moving in.
Then the appraisal comes back:
Purchase price: $400,000
Appraised value: $380,000
Now what?
The first thing to understand is that a low appraisal does not automatically mean the transaction is dead.
It also doesn’t necessarily mean you need to bring an additional $20,000 to closing.
There may be several ways to address the difference depending on the mortgage program, purchase agreement, down payment, appraisal contingency and willingness of the buyer and seller to negotiate.
Let’s break down what actually happens.
How Does a Low Appraisal Affect Your Mortgage?
Mortgage financing is generally based on the lower of the purchase price or appraised value when calculating loan-to-value on a purchase transaction.
That’s an extremely important concept.
Let’s use a simple example.
You’re buying a home for:
$400,000
You’re putting 5% down, so you expected:
Down payment: $20,000
Mortgage: $380,000
Now the appraisal comes back at:
$380,000
The lender generally doesn’t continue calculating the loan as though the property were worth $400,000.
Instead, the lower appraised value becomes relevant to the loan-to-value calculation.
That’s why a low appraisal can change how much you can borrow.
But here’s where buyers sometimes misunderstand what happens next.
Do You Automatically Need to Pay the Entire Appraisal Gap in Cash?
Not necessarily.
This deserves emphasis because buyers often hear:
“The appraisal is $20,000 low, so you need another $20,000.”
That can be wrong.
Your existing down payment may absorb some or potentially all of the difference depending on the mortgage program, required LTV and how much you were originally putting down.
Let’s look at two very different examples.
Example 1: 5% Down and a $20,000 Low Appraisal
Suppose:
Purchase price: $400,000
Original down payment: 5% or $20,000
Original loan amount: $380,000
The appraisal comes back at:
$380,000
If the mortgage program allows a maximum 95% LTV for the transaction, 95% of $380,000 is:
$361,000
If the seller refuses to reduce the $400,000 purchase price, the buyer would need to cover the difference between the purchase price and available financing.
That could mean substantially more cash than originally planned.
This is where the appraisal gap becomes a very real issue.
Example 2: 20% Down and the Same $20,000 Low Appraisal
Now let’s change only one thing.
The buyer was originally planning to put 20% down.
Purchase price: $400,000
Original down payment: $80,000
Original loan: $320,000
The appraisal comes back at:
$380,000
The buyer’s $320,000 mortgage is only about 84.2% of the appraised value.
Depending on the mortgage program and desired loan structure, the buyer may have significantly more flexibility than the 5%-down borrower.
They don’t necessarily need to add $20,000 on top of the $80,000 they already planned to bring.
Instead, we may be able to restructure the financing.
That’s why the statement:
“Your appraisal came in $20,000 low, so bring another $20,000.”
is not universally correct.
We have to look at the actual loan.
What Are Your Options When an Appraisal Comes in Low?
There are several potential paths.
Which one makes sense depends on the transaction.
Option 1: The Seller Reduces the Purchase Price
This is obviously the simplest outcome for the buyer.
Suppose:
Purchase price: $400,000
Appraisal: $385,000
The seller agrees to reduce the purchase price to $385,000.
Now the contract price and appraised value match.
Problem solved from a valuation standpoint.
Of course, sellers aren’t required to happily reduce their price simply because an appraisal came in low.
In a competitive market, they may believe another buyer will pay more.
That’s when negotiations become important.
Option 2: The Buyer Covers Some or All of the Difference
The buyer may decide the house is worth more to them than the appraised value.
Suppose:
Purchase price: $400,000
Appraisal: $390,000
The seller won’t move.
The buyer still wants the house.
Depending on the mortgage structure, the buyer may decide to bring additional funds to make the transaction work.
But buyers should understand exactly what they’re doing.
They’re paying a price above the appraiser’s opinion of market value.
That isn’t automatically a terrible decision.
Homes aren’t stocks with an exact price displayed on a screen.
Two qualified appraisers could potentially develop somewhat different opinions of value.
And a buyer may place additional value on a specific location, lot, school district, layout or feature.
But the buyer should understand the financial implications before deciding to cover an appraisal gap.
Option 3: The Buyer and Seller Meet in the Middle
This is extremely common.
Let’s say:
Purchase price: $400,000
Appraisal: $380,000
Instead of one side absorbing the entire $20,000 difference, the parties renegotiate.
Perhaps the seller agrees to:
$390,000
The buyer accepts the new price and works with the mortgage company to determine what additional funds, if any, are needed under the revised financing.
The seller gives up $10,000.
The buyer absorbs some of the remaining difference.
Neither side gets exactly what they originally wanted, but the transaction stays together.
Option 4: Request a Reconsideration of Value
A low appraisal isn’t necessarily the final word if there is legitimate information that may support a different value conclusion.
There is a process commonly referred to as a Reconsideration of Value, or ROV.
This isn’t:
“We don’t like the appraisal. Please make it higher.”
There needs to be a substantive reason to reconsider the value.
For example, there may be:
- Relevant comparable sales that weren’t considered
- Incorrect property information
- Errors involving square footage or features
- Material information that may affect the valuation
- Other legitimate appraisal concerns
The appropriate information can be submitted through the applicable process for review.
But buyers should have realistic expectations.
An ROV is not a negotiation with the appraiser.
The fact that the buyer offered $400,000 doesn’t prove the property is worth $400,000.
We need actual market or property information supporting the requested reconsideration.
Can the Real Estate Agent Provide Better Comparable Sales?
Potentially, and this is one area where an experienced real estate agent can be extremely helpful.
If the appraisal comes in low, the buyer’s agent may review the comparable sales used by the appraiser and identify other potentially relevant sales.
Maybe a nearby comparable closed very recently.
Maybe an important property feature wasn’t accurately reflected.
Maybe one of the appraiser’s comparable properties is materially different from the subject.
That information can potentially be useful in an ROV request.
But again, the goal isn’t to bombard the appraiser with every home that sold for a higher price.
The comparable sales need to actually be relevant.
Can You Just Order Another Appraisal?
Usually, you can’t simply keep ordering appraisals until you get the number you want.
Mortgage appraisal independence requirements exist for a reason.
The lender can’t shop around for an appraiser willing to hit the purchase price.
There are circumstances where a new appraisal may be permitted or required, but it isn’t normally as simple as:
“That one was too low. Let’s try another appraiser.”
If there is a legitimate issue with an appraisal, the proper review or reconsideration process should be followed.
What Is an Appraisal Gap Guarantee?
During competitive housing markets, buyers sometimes include an appraisal gap guarantee in their offer.
The exact language belongs in the real estate contract, so buyers should discuss it with their real estate agent and, when appropriate, an attorney.
Conceptually, though, it means the buyer agrees to cover some amount of difference if the appraisal comes in below the purchase price.
For example, a buyer might offer:
$425,000 with an appraisal gap guarantee up to $10,000.
If the property appraises at $420,000, the buyer may have agreed to cover the $5,000 difference.
If it appraises at $400,000, the contract terms determine what happens beyond the $10,000 commitment.
This can make an offer more attractive to a seller because it reduces some of the uncertainty surrounding the appraisal.
But buyers need to understand exactly what they’re promising.
Don’t Make an Appraisal Gap Guarantee Without Talking to Your Mortgage Broker
This is especially important.
Before guaranteeing that you’ll cover a $10,000, $20,000 or larger appraisal gap, we should determine what that would actually do to your mortgage.
Where will the additional money come from?
Will you still have enough funds for:
- Down payment
- Closing costs
- Prepaid taxes and insurance
- Required reserves
- Moving expenses
- Emergency savings
Will the lower appraisal affect mortgage insurance?
Does the loan amount need to change?
Does the revised LTV change pricing or eligibility?
These are questions that should be answered before you promise additional money in a purchase agreement.
A strong mortgage pre-approval should involve more than simply calculating the maximum purchase price.
It should also help you understand how different offer structures could affect your financing.
Can Seller Concessions Fix a Low Appraisal?
Not directly.
Seller concessions can be extremely useful for helping a buyer with eligible closing costs and prepaid expenses, but they don’t simply increase the appraised value of the property.
Suppose:
Purchase price: $400,000
Appraisal: $385,000
The seller can’t solve the valuation problem by saying:
“I’ll give you a $15,000 seller concession.”
We still have a property valued at $385,000 for mortgage purposes.
However, concessions can sometimes become part of a broader renegotiation strategy.
For example, changing the purchase price and seller concessions together may affect how much cash the buyer needs at closing.
That’s why the entire transaction should be recalculated rather than focusing on one number.
What Happens to Your Down Payment If the Price Changes?
This is another reason to involve the mortgage company when negotiating after a low appraisal.
Suppose the seller reduces the purchase price.
Your required down payment may change.
Your loan amount may change.
Mortgage insurance could change.
Your closing costs or prepaid items could change.
The amount of cash you need at closing could change.
Don’t assume that a $10,000 reduction in purchase price means you’ll automatically bring exactly $10,000 less to closing.
Mortgage calculations don’t always work dollar-for-dollar like that.
We need to rerun the loan.
What If the Appraisal Comes in Higher Than the Purchase Price?
This is the outcome buyers love.
Suppose:
Purchase price: $400,000
Appraised value: $425,000
Did you just make $25,000?
Not exactly.
You haven’t sold the property, and an appraisal is an opinion of value rather than cash deposited into your account.
But it can certainly feel good knowing the appraisal supports a value above the price you’ve agreed to pay.
Here’s the important mortgage piece:
On a typical purchase transaction, you generally don’t get to use that higher appraisal to reduce your required down payment as though the seller handed you $25,000 of equity.
The purchase-price calculation still matters.
So if you agreed to put 5% down on a $400,000 purchase, a $425,000 appraisal doesn’t generally mean you suddenly get to borrow based on $425,000 and eliminate your down payment.
Does a Higher Appraisal Mean You Instantly Have Equity?
Conceptually, you may have purchased the property below the appraiser’s opinion of market value.
That’s certainly positive.
But be careful with the phrase “instant equity.”
Home values can change.
Appraisals are opinions of value as of a particular effective date.
Selling a property involves transaction costs.
And future lenders may require a new valuation depending on what you’re trying to do.
So I wouldn’t treat a high appraisal like money in the bank.
I would treat it as reassuring evidence that the purchase price appears well supported.
What Is an Appraisal Waiver?
Now we get into something that has become increasingly common with Conventional mortgages.
Sometimes an automated underwriting system may determine that a traditional appraisal isn’t required for an eligible transaction.
This is commonly referred to as an appraisal waiver or property inspection waiver, depending on the applicable system and terminology.
When available and accepted, the borrower may be able to proceed without a traditional appraisal.
That can potentially:
- Save the appraisal fee
- Reduce one source of transaction uncertainty
- Speed up part of the mortgage process
- Eliminate the risk of a traditional appraisal coming in below the purchase price
Sounds great.
But there’s an important catch.
An Appraisal Waiver Does Not Mean the House Has Been Inspected
This is one of the most important points in the entire article.
Suppose your mortgage receives an appraisal waiver.
Fantastic.
That does not mean:
- Someone inspected the roof
- Someone checked the furnace
- Someone looked for water intrusion
- Someone evaluated the electrical system
- Someone inspected the foundation
- Someone checked the plumbing
- Someone determined the home is in excellent condition
It means the mortgage transaction satisfied the applicable requirements to proceed without the traditional appraisal process.
That’s all.
The appraisal waiver has nothing to do with whether you should obtain a home inspection.
Should You Still Get a Home Inspection With an Appraisal Waiver?
The appraisal waiver and home inspection answer completely different questions, so receiving a waiver doesn’t eliminate the reason someone might want an inspection.
In fact, this can make the distinction even easier to understand.
With a traditional appraisal:
Lender valuation process + buyer inspection process
With an appraisal waiver:
No traditional appraisal + buyer inspection process
The buyer’s need to understand the physical condition of the house hasn’t changed.
Can You Get an Appraisal Waiver on Every Conventional Loan?
No.
Appraisal waivers are generally determined through the applicable automated underwriting and property-data systems based on eligibility requirements and available information.
You can’t simply demand one because you don’t want to pay for an appraisal.
A borrower may receive one transaction with a waiver and another transaction without one.
Property, loan characteristics, available data and underwriting findings can all matter.
That’s why we don’t promise an appraisal waiver before the loan has actually been evaluated.
Are Appraisal Waivers Available With FHA or VA Loans?
FHA and VA have their own appraisal requirements and processes, so you shouldn’t assume a Conventional appraisal waiver applies to those programs.
If you’re comparing mortgage options, this is another reason to evaluate the complete financing structure rather than selecting a loan solely because of one feature.
For many borrowers, choosing between FHA and Conventional financing involves credit, down payment, mortgage insurance, interest rate, property considerations and long-term cost.
The appraisal is just one part of that comparison.
What Happens If You Waive the Appraisal Contingency?
This is different from receiving an appraisal waiver from the mortgage underwriting system.
The terminology sounds similar, but these are two completely different things.
Appraisal Waiver
The mortgage process determines that a traditional appraisal isn’t required.
Waiving the Appraisal Contingency
The buyer agrees through the purchase contract to give up or modify certain protections related to the property’s appraised value.
Those are not interchangeable.
A buyer could waive an appraisal contingency and still be required by the lender to obtain an appraisal.
That’s when things can get financially uncomfortable.
Suppose you offer $450,000 and waive your appraisal contingency.
The lender requires an appraisal.
The home appraises at $415,000.
Now you potentially have a $35,000 valuation difference and fewer contractual options than you would have had with an appraisal contingency.
This is why buyers should understand the financial consequences before waiving protections simply to make an offer look stronger.
A Strong Offer Isn’t Just the Highest Offer
In competitive markets, buyers naturally want their offer to stand out.
That may involve:
- Purchase price
- Closing date
- Earnest money
- Financing
- Appraisal terms
- Inspection terms
- Occupancy
- Seller concessions
- Other contract provisions
But making an offer stronger shouldn’t mean accepting financial risks you don’t understand.
Sometimes a buyer can comfortably cover an appraisal gap.
Sometimes they can’t.
Sometimes an appraisal contingency is extremely important.
Sometimes the buyer’s financial position provides more flexibility.
There isn’t one perfect offer structure for every buyer.
The mortgage strategy and real estate strategy should work together.
Inspection Contingency and Appraisal Contingency Are Different Too
This is another distinction worth making.
An inspection contingency generally addresses the buyer’s rights surrounding the property’s condition and inspection results.
An appraisal contingency generally addresses what happens if the property’s appraised value doesn’t support the agreed-upon price.
A house could have:
A fantastic inspection and a low appraisal.
Or:
A terrible inspection and a perfect appraisal.
One contingency doesn’t automatically protect you from the problem addressed by the other.
This is why buyers should understand the purchase agreement they’re signing rather than assuming every contingency means:
“I can get out for anything.”
Your real estate agent or attorney can explain the contractual protections and obligations in your specific agreement.
Which Comes First: Inspection or Appraisal?
In many transactions, the home inspection happens first.
There is a practical reason for that.
Imagine the buyer completes an inspection and discovers a major issue that causes them to terminate the transaction under the terms of their purchase agreement.
If the appraisal hasn’t been completed yet, they may avoid spending money on an appraisal for a property they’re no longer purchasing.
But we also don’t want to wait so long that the appraisal delays closing.
That’s why coordination matters.
Once the offer is accepted, the buyer, agent and mortgage team should understand the timeline for:
Inspection → appraisal → underwriting → closing.
This is part of what makes an organized mortgage process so important.
What If Both the Inspection and Appraisal Find Problems?
Then we need to separate the issues.
Suppose the inspector discovers:
- Aging furnace
- Plumbing leak
- Evidence of basement moisture
Meanwhile, the appraisal:
- Comes in $10,000 low
- Requires an exterior paint repair
Now we have two different negotiations happening around the same property.
The buyer may be concerned about condition.
The lender has an appraisal requirement.
And the purchase price may no longer be supported by the appraised value.
This is where experienced professionals become especially valuable.
Instead of treating everything as one giant problem, we identify each issue and determine what needs to happen for:
The buyer to remain comfortable with the property.
The mortgage to remain eligible.
The buyer and seller to reach an agreement.
Sometimes the transaction still works perfectly well.
Sometimes the numbers need to change.
And sometimes walking away may ultimately be the right decision under the terms of the purchase agreement.
Don’t Let the Appraisal Distract You From the Inspection—or Vice Versa
It’s easy for buyers to focus on whichever report arrives first.
A 40-page inspection report can make every small issue feel terrifying.
A low appraisal can suddenly make the entire transaction feel like a financial disaster.
Neither reaction is particularly useful without context.
Instead, ask:
What did we actually learn?
Is the inspection issue minor maintenance or a major structural concern?
Is the appraisal $2,000 low or $40,000 low?
Is there strong evidence supporting an ROV?
Will the seller negotiate?
Can the financing be restructured?
Does the buyer still want the house after understanding everything?
Those are the questions that move the transaction forward.
What Does a Home Inspector Actually Look At?
Now that we’ve covered what happens when an appraisal comes in low, let’s turn our attention to the other side of the equation:
What are you actually buying?
A home inspection is designed to give the buyer a better understanding of the property’s physical condition.
That doesn’t mean the inspector can predict every future repair.
It doesn’t mean they’ll find every hidden defect.
And it certainly doesn’t mean an inspection report containing 40 pages of observations means you’re buying a terrible house.
Homes have issues.
Even relatively new homes can have them.
The purpose of the inspection is to help you identify and understand those issues before you own the property.
What Is Usually Included in a Home Inspection?
The exact scope depends on the inspector and the services you’ve hired them to perform, but a typical home inspection may evaluate visible and accessible components of the property such as:
- Roof and exterior
- Foundation
- Basement or crawlspace
- Attic
- Electrical system
- Plumbing system
- Heating system
- Air conditioning
- Windows and doors
- Walls and ceilings
- Floors
- Stairs and railings
- Insulation and ventilation
- Built-in appliances
- Drainage around the property
- Other visible structural and mechanical components
The inspector is looking for evidence of defects, deterioration, improper installation, safety concerns and systems that may not be functioning as expected.
But there are limits.
A Home Inspection Isn’t X-Ray Vision
This is worth understanding before you receive the report.
A standard home inspection is generally based on visible and accessible conditions.
The inspector typically isn’t going to:
- Tear open drywall
- Remove flooring
- Dig up the foundation
- Disassemble the furnace
- Open finished ceilings
- Excavate the sewer line
- Move all of the seller’s belongings
- Determine what’s happening inside every concealed wall
So an inspection can dramatically improve your understanding of the property without guaranteeing that absolutely nothing is wrong.
A house can have a good inspection and still develop a problem six months later.
That’s homeownership.
Should You Attend the Home Inspection?
When possible, I think there can be real value in buyers attending at least part of the inspection, assuming the inspector and circumstances allow it.
Reading:
“Evidence of moisture observed near northwest basement wall”
on a report can sound terrifying.
Standing there while the inspector shows you exactly what they’re talking about and explains the context can be completely different.
It also gives buyers an opportunity to learn about the home.
Where is the main water shutoff?
Where is the electrical panel?
How old does the furnace appear to be?
What maintenance should you plan for?
Which findings are significant?
Which are relatively minor?
A good inspection can be educational, especially for a first-time home buyer who hasn’t previously been responsible for maintaining a house.
Don’t Panic When You See the Inspection Report
Modern inspection reports can be extremely detailed.
Photos.
Warnings.
Recommendations.
Safety notices.
Maintenance items.
Potential defects.
Pages and pages of information.
A first-time buyer opens the report and thinks:
“This house is falling apart.”
Then you discover that half the report consists of things like:
- Loose door handle
- Missing outlet cover
- Slow bathroom drain
- Cracked caulk
- Minor grading recommendation
- GFCI recommendation
- Aging but functional equipment
That doesn’t mean those items should be ignored.
It means they need context.
There’s a big difference between:
“The furnace is 18 years old.”
and:
“The heat exchanger is cracked and the furnace should not be operated.”
One is information that helps you plan for future replacement.
The other may be an immediate concern.
Focus on the Big Things First
When reviewing an inspection, buyers often benefit from separating findings into categories.
Major or potentially expensive concerns
These could include things like:
- Significant foundation problems
- Major roof issues
- Serious water intrusion
- Substantial electrical defects
- Failed heating systems
- Major plumbing problems
- Sewer-line failures
- Significant structural concerns
Safety concerns
These may require more immediate attention depending on the issue.
Deferred maintenance
The house may function today but need work in the foreseeable future.
Minor repairs
Things that should eventually be addressed but probably shouldn’t determine whether you buy the home.
Cosmetic items
These are generally personal preference rather than meaningful property defects.
That doesn’t mean buyers should ignore small problems.
It means a loose cabinet hinge probably shouldn’t receive the same attention as a cracked foundation wall.
What If the Inspection Finds a Major Problem?
This is where your purchase agreement becomes extremely important.
Depending on the contract and inspection contingency, the buyer may potentially have options such as:
- Accepting the property as-is
- Asking the seller to make repairs
- Asking for a price reduction
- Negotiating a seller concession or credit when permitted
- Requesting additional evaluation
- Renegotiating other terms
- Potentially terminating the transaction under the applicable contract provisions
The mortgage company doesn’t decide what rights you have under your inspection contingency.
That’s a contractual issue between the buyer and seller.
Your real estate agent or attorney should guide you through the contract.
But changes resulting from inspection negotiations can affect the mortgage, which is why your loan officer needs to know when the financial terms change.
Repair or Seller Credit: Which Is Better?
Suppose the inspection reveals that the furnace is near failure.
The buyer asks the seller to do something about it.
There are two very different approaches.
Seller makes the repair
The seller replaces or repairs the furnace before closing.
Seller provides a concession
Instead of performing the work, the seller agrees to contribute an amount toward eligible buyer closing costs, subject to the mortgage program’s rules and limits.
Which is better?
It depends.
If the buyer already has enough seller concessions to cover all eligible costs, another credit may provide little or no additional benefit.
Seller concessions generally aren’t a pile of cash the buyer receives after closing.
They need to be structured within the applicable mortgage and closing-cost rules.
That’s why understanding seller concessions and how they work with a mortgage is important before agreeing to a credit.
Can the Seller Just Give You Cash After Closing for Repairs?
Generally, don’t structure side deals involving the seller secretly giving the buyer money outside the disclosed transaction.
The lender needs to know the actual terms of the purchase.
If the buyer and seller negotiate financial changes, those changes should be properly documented and disclosed to the appropriate parties.
A handshake agreement that says:
“We’ll close at the original price and I’ll Venmo you $8,000 afterward for the roof”
is not how you want to handle a mortgage transaction.
If the inspection changes the financial agreement, tell your mortgage and real estate professionals so it can be structured correctly.
Can Inspection Repairs Affect the Appraisal?
Potentially.
Normally, the lender isn’t using your private home inspection report as a substitute for the appraisal.
But information discovered during an inspection can sometimes lead to issues that affect the transaction more broadly.
For example, suppose an inspection uncovers a serious structural problem.
Now the buyer and seller negotiate repairs.
Depending on the issue, mortgage program and transaction, the condition may become relevant to the property’s eligibility or appraisal.
Or suppose the purchase agreement is amended because of the inspection.
That amendment may need to be provided to the mortgage company.
The important thing is not to assume:
“The inspection has nothing to do with my lender.”
The inspection and appraisal are separate, but what happens because of the inspection can sometimes affect the mortgage.
What Is a Sewer Scope?
This is one specialized inspection I think Michigan homebuyers should at least understand.
A standard home inspection generally doesn’t involve running a camera through the entire underground sewer lateral.
A sewer scope does.
A camera is inserted into the sewer line to evaluate its condition and potentially identify issues such as:
- Cracks
- Root intrusion
- Blockages
- Deteriorated pipe
- Separated connections
- Bellies or low spots
- Other damage
Why does this matter?
Because the house could look beautiful.
The inspection could be relatively clean.
The appraisal could support the purchase price.
And you could still have a very expensive problem underground.
Older homes can make this especially worth considering.
Whether you need a sewer scope depends on the property and circumstances, but it’s a good example of why buyers shouldn’t assume a standard inspection covers everything.
What About Septic Systems and Wells?
If you’re buying a property with a private well or septic system, there may be additional inspections, testing or mortgage requirements to consider.
This is more common in parts of Michigan where homes aren’t connected to municipal water and sewer.
Depending on the property and mortgage program, issues involving:
- Water quality
- Well condition
- Septic condition
- Distance requirements
- Local health requirements
may become important.
These aren’t necessarily part of a standard home inspection.
If you’re considering a rural or semi-rural property, we want to identify those features early so everyone knows what additional evaluations may be needed.
Should You Test for Radon in Michigan?
Radon testing is another service that may be offered separately from the standard home inspection.
Radon is a naturally occurring radioactive gas that can enter homes from the soil and cannot be detected by sight or smell.
The only way to know the home’s radon level is to test for it.
A buyer may choose to include radon testing as part of their inspection process or arrange it separately.
If elevated levels are found, mitigation systems can often be installed.
The key point for our appraisal-versus-inspection discussion is this:
An appraisal isn’t a radon test.
An appraiser walking through the property cannot tell you the home’s radon level.
What About Mold?
This is another area where terminology can get confusing.
A home inspector may observe visible conditions suggesting moisture or possible microbial growth and recommend further evaluation.
That doesn’t necessarily mean a standard inspection includes comprehensive mold testing.
If there is evidence of significant moisture, past flooding, unusual odors or visible growth, a buyer may decide to obtain additional evaluation from an appropriate professional.
And again:
A normal appraisal does not mean the house has been tested for mold.
What About Lead-Based Paint?
Homes built before 1978 can involve additional lead-based paint considerations.
As we discussed earlier, defective painted surfaces can become particularly important with FHA financing.
But an appraiser observing peeling paint isn’t the same thing as conducting a comprehensive lead inspection or risk assessment.
If a buyer has concerns about lead-based paint—especially in an older Michigan home—they should understand what testing or evaluation they may want beyond the mortgage appraisal.
What About Asbestos?
Older homes may contain materials that could include asbestos.
Potential examples can include certain older:
- Insulation
- Floor tiles
- Pipe insulation
- Siding
- Ceiling materials
- Other building products
A standard home inspection doesn’t necessarily involve laboratory testing of materials.
And an appraisal certainly isn’t an asbestos inspection.
If a buyer has a specific concern, specialized testing may be appropriate.
Should You Get a Chimney Inspection?
If the home has a fireplace or chimney, a standard home inspector may observe accessible components and recommend further evaluation when appropriate.
A dedicated chimney inspection can provide a more specialized assessment.
The same principle applies to many parts of a house.
A home inspector is a generalist.
When they identify something concerning, they may recommend a specialist.
That could be a:
- Roofer
- Electrician
- Plumber
- HVAC contractor
- Structural engineer
- Foundation specialist
- Chimney professional
- Sewer professional
- Environmental specialist
The inspection can tell you where to look deeper.
Should New Construction Homes Be Inspected?
This surprises some buyers.
They’ll say:
“It’s brand new. What is there to inspect?”
Potentially plenty.
New doesn’t automatically mean perfect.
A newly constructed home involves many trades, materials and stages of construction.
An inspection may identify items involving:
- Electrical work
- Plumbing
- HVAC
- Insulation
- Roof installation
- Grading and drainage
- Windows and doors
- Finish work
- Other construction details
A builder warranty can be valuable, but discovering an issue before closing can be much easier than discovering it after you’ve moved in.
Some buyers also choose inspections at different stages of construction depending on the project and what the builder permits.
Does a New Construction Home Still Need an Appraisal?
If the mortgage program requires an appraisal, the fact that the home is newly constructed doesn’t eliminate the lender’s need to establish an acceptable property value.
New construction appraisals can be interesting because comparable sales may sometimes be more complicated.
Suppose you’re buying one of the first homes in a new development.
There may not be dozens of recently closed identical homes available as comparables.
The appraiser still needs to develop a supported opinion of value using appropriate appraisal methodology and available market information.
This is another reason the builder’s asking price isn’t automatically the appraised value.
What About Builder Upgrades?
This is a big one with new construction.
Suppose the base home costs:
$450,000
Then you add:
- Premium lot: $25,000
- Finished basement: $35,000
- Upgraded kitchen: $20,000
- Flooring package: $12,000
- Landscaping: $10,000
Now your contract price is:
$552,000
Does that automatically mean the house will appraise for $552,000?
No.
Upgrades don’t necessarily contribute to market value dollar-for-dollar.
You may personally love the $20,000 kitchen package.
The market may not recognize an additional $20,000 of value from it.
That’s why buyers making substantial upgrades should understand the possibility of an appraisal gap before committing significant funds.
What About a Final Walkthrough?
The final walkthrough is another thing that gets confused with an inspection.
It’s not the same.
A home inspection generally occurs earlier in the transaction and evaluates the property’s condition.
A final walkthrough generally happens shortly before closing so the buyer can confirm things such as:
- The property remains in expected condition
- Agreed-upon repairs appear to have been completed
- The seller has removed belongings as required
- No obvious new damage has occurred
- Included items remain with the property
The walkthrough isn’t normally the time to perform your first comprehensive inspection of the house.
By then, you’re usually very close to closing.
What If Something Is Wrong During the Final Walkthrough?
Don’t ignore it and assume you’ll figure it out after closing.
Tell your real estate agent immediately.
Depending on the issue and purchase agreement, the parties may need to determine how it will be handled.
If the resolution changes the financial terms of the transaction, the mortgage company may also need to know.
This is especially important because last-minute changes can potentially affect closing documents and the amount of money required at closing.
Should You Waive the Home Inspection to Win a Bidding War?
This is ultimately a real estate and risk decision rather than a mortgage decision.
But buyers should understand exactly what they’re giving up.
Waiving or limiting inspection protections may make an offer more attractive to a seller.
It can also mean accepting substantially more property-condition risk.
The right decision depends on things like:
- The buyer’s financial resources
- Age and apparent condition of the home
- Competitiveness of the market
- Contract language
- Buyer’s risk tolerance
- Other available inspection strategies
What I wouldn’t do is assume:
“The lender is ordering an appraisal anyway, so I don’t need an inspection.”
Those two things are not interchangeable.
Inspection Problems and Mortgage Problems Are Not the Same Thing
This is probably the best way to think about the entire process.
Suppose the inspector says:
The furnace is old.
That may be important to the buyer.
It doesn’t automatically mean the mortgage can’t close.
Suppose the appraiser says:
A required property condition must be corrected before closing.
Now we may have a mortgage eligibility issue.
Suppose the inspector finds:
Major structural movement.
That begins as an inspection issue, but depending on what happens next, it could potentially become relevant to the appraisal, property eligibility, insurance or mortgage transaction.
The categories can overlap.
But they don’t start from the same place.
Appraisal, Inspection and Underwriting: Three Different Jobs
At this point, it helps to separate all three.
The Appraiser
Primarily evaluates property value and applicable property requirements for the mortgage.
The Home Inspector
Evaluates the physical condition of the property for the buyer.
The Mortgage Underwriter
Evaluates whether the complete mortgage transaction satisfies applicable lending requirements.
That includes reviewing things such as:
- Income
- Credit
- Assets
- Debts
- Property
- Appraisal
- Loan program
- Documentation
This is why mortgage underwriting can still request something involving the property even after the appraisal has been completed.
Everyone has a different role.
Don’t Try to Make One Professional Do Another Professional’s Job
Your mortgage broker isn’t your home inspector.
Your inspector isn’t your appraiser.
Your appraiser isn’t your real estate agent.
Your real estate agent isn’t your attorney.
Your attorney isn’t your mortgage underwriter.
The best transactions happen when the right professional handles the right issue and everyone communicates when those issues overlap.
As a buyer, you don’t need to become an expert in every one of these fields.
You just need to understand who to ask when something comes up.
The Goal Isn’t a Perfect House
Almost every home has something wrong with it.
Even a brand-new home can have a punch list.
The goal of the inspection isn’t necessarily to find a house with zero defects.
It’s to help you make an informed decision.
Can you live with the issues?
Can they be repaired?
What might they cost?
Does the seller need to address something?
Should you obtain another professional opinion?
Does the property still make sense at the agreed-upon price?
Those are much more useful questions than:
“Did the house pass inspection?”
Because unlike the way people often talk about it, a home inspection usually isn’t a simple pass-or-fail test.
It’s information.
And what you do with that information can be just as important as what’s written in the report.
Appraisal vs. Home Inspection: Cost, Timing and What Michigan Buyers Should Expect
By now, the biggest distinction should be clear:
An appraisal helps answer whether the property’s value and condition support the mortgage.
A home inspection helps you understand the condition of the home you’re buying.
Both can uncover problems.
Both can affect a real estate transaction.
But they’re performed for different reasons, by different professionals, and the results can have very different consequences.
Let’s finish by looking at how these pieces fit together from accepted offer through closing—and answer some of the questions Michigan homebuyers ask most often.
How Much Does a Home Appraisal Cost in Michigan?
There isn’t one universal appraisal fee.
The cost can vary depending on factors such as:
- Property type
- Location
- Complexity
- Size
- Loan program
- Required appraisal product
- Availability of qualified appraisers
- Whether additional inspections or services are necessary
A typical single-family home appraisal may cost several hundred dollars, but unusual or complex properties can cost more.
Rather than focusing on an advertised appraisal price from somewhere online, look at the appraisal fee disclosed for your specific mortgage transaction.
The appraisal charge is one of the costs you’ll generally see when reviewing your Loan Estimate.
And remember: an appraisal fee and a home inspection fee are two separate expenses.
How Much Does a Home Inspection Cost in Michigan?
Home inspection pricing also varies.
Factors can include:
- Size of the house
- Age of the property
- Location
- Type of home
- Inspector
- Services included
Additional services can increase the total cost.
For example, you may choose to add:
- Radon testing
- Sewer scope
- Mold evaluation
- Well testing
- Septic evaluation
- Pest inspection
- Other specialized services
A buyer may look at the inspection price and think:
“That’s a lot of money for a house I don’t even own yet.”
That’s understandable.
But you’re about to potentially spend hundreds of thousands of dollars on the property.
Learning as much as reasonably possible about its condition before closing can provide valuable information for that decision.
When Do You Pay for the Appraisal?
The appraisal fee may be collected before the appraisal is performed or otherwise handled through the mortgage process.
This is one reason buyers can have expenses before closing.
Not every dollar associated with buying a home waits until the day you receive the keys.
Depending on the transaction, you may have already paid for things such as:
- Earnest money deposit
- Home inspection
- Appraisal
- Specialized inspections or testing
Then you’ll have the remaining applicable down payment, closing costs and prepaid expenses due through the closing.
This is why I don’t like reducing the homebuying conversation to:
“How much is my down payment?”
The better question is:
“How much money should I realistically have available for the entire transaction?”
When Do You Pay for the Home Inspection?
Home inspectors are generally paid directly by the buyer according to the inspector’s payment terms.
That often occurs around the time the inspection is performed.
The inspection fee usually isn’t something you’re financing into your standard mortgage just because it’s related to buying the house.
So when budgeting for a purchase, buyers should have some accessible funds available for expenses that can occur before closing.
How Long Does an Appraisal Take?
There isn’t a universal turnaround time.
The timeline can depend on:
- Appraiser availability
- Property location
- Property complexity
- Market conditions
- Loan program
- Access to the property
- Availability of comparable sales
- Whether additional information is needed
The appraisal process involves more than the appraiser walking through the house.
The appraiser also needs to complete the valuation analysis and appraisal report.
Once the report is received, it may also need to go through lender or underwriting review.
That’s why:
“The appraiser was at the house yesterday”
doesn’t necessarily mean:
“The appraisal is completely cleared today.”
How Long Does a Home Inspection Take?
The actual inspection may take several hours depending on the size, age and complexity of the property.
That’s one major difference from an appraisal.
The inspector may spend considerable time evaluating accessible components of the home, documenting findings and preparing a detailed report.
Buyers should ask the inspector when they can expect the completed report because inspection contingencies often operate within specific contractual timelines.
You don’t want to discover that you had three days to address an inspection issue after waiting four days to review the report.
Your real estate agent should help you keep track of the deadlines contained in your purchase agreement.
Who Gets the Appraisal Report?
Because the appraisal is obtained as part of the mortgage process, borrowers generally receive a copy of the appraisal or valuation information as required by applicable rules.
That doesn’t mean you should only look at the final value.
Read the report.
You may see:
- Subject property information
- Comparable sales
- Adjustments
- Property photographs
- Market information
- Property-condition comments
- Appraiser observations
- Final opinion of value
You don’t need to become an appraiser to understand the report.
But it’s worth knowing how the appraiser arrived at the value.
Who Gets the Home Inspection Report?
The home inspection is generally obtained by the buyer, and the report belongs within that inspection relationship subject to the inspector’s agreement and applicable circumstances.
This is important because the inspection report isn’t automatically the lender’s appraisal report.
Buyers sometimes assume every document generated during the purchase gets sent directly to the mortgage underwriter.
That’s not necessarily the case.
However, as we discussed earlier, issues discovered during an inspection can sometimes lead to contract changes, repairs or other circumstances that become relevant to the mortgage.
Does the Mortgage Company Need My Home Inspection Report?
Not normally simply because you chose to have the home inspected.
The lender has its own appraisal and underwriting requirements.
But don’t interpret that as:
“I should hide serious property issues from the lender.”
If the inspection results lead to amendments, repairs, credits, concessions or other changes to the transaction, those changes may need to be disclosed and reviewed.
The mortgage needs to reflect the actual transaction taking place.
Can You Use an Appraisal From Another Lender?
Sometimes borrowers switch lenders after an appraisal has already been completed and ask:
“Can’t you just use the appraisal I already paid for?”
The answer depends on the loan program, appraisal circumstances and applicable transfer requirements.
There are situations where an appraisal may potentially be transferred or used by another lender, and other situations where a new appraisal may be necessary.
So don’t assume either way.
If you’re considering changing lenders after the appraisal has been completed, ask the new mortgage company to review the situation before making the switch.
Can You Use an Old Home Inspection?
That’s really a different question.
Suppose the seller had an inspection performed six months ago and gives you the report.
Is that useful?
Sure.
Would I automatically treat it as equivalent to an inspection performed specifically for you today?
I wouldn’t.
The condition of a property can change.
The previous inspection may have had a different scope.
You may not have the same contractual relationship with that inspector.
Repairs may have been made—or problems may have developed—since the report was completed.
A previous report can provide information.
Whether it’s enough information for you to rely on when purchasing the property is a separate decision.
What Happens to the Appraisal If the Deal Falls Apart?
Generally, you’ve paid for a professional service that has already been performed.
If the purchase transaction falls apart afterward, you shouldn’t assume the appraisal fee will automatically be refunded.
The same basic concept applies to the home inspection.
You paid the inspector to inspect the property and provide information.
If you decide not to buy the house because of what the inspector discovered, the inspection may have done exactly what you hired the inspector to do.
You spent several hundred dollars to potentially avoid making a much more expensive mistake.
That’s not necessarily money wasted.
Can the Next Buyer Use Your Inspection?
Don’t assume your private inspection simply becomes the next buyer’s inspection.
Inspection reports, agreements and reliance rights can involve the inspector’s contractual terms.
The next buyer may decide to obtain their own inspection.
And from that buyer’s perspective, that may be the smarter choice.
When you’re making a purchase this large, relying exclusively on someone else’s old report to save a few hundred dollars can create unnecessary risk.
Can the Seller See the Appraisal?
This can depend on how information is shared during the transaction.
If an appraisal comes in low and the buyer wants the seller to reduce the purchase price, information from the appraisal may naturally become relevant to negotiations.
But the seller doesn’t control the appraisal simply because they own the property.
The appraisal was obtained in connection with the buyer’s mortgage transaction.
Your real estate agent can help determine what information should be shared during negotiations.
What Happens If the Seller Disagrees With the Appraisal?
They’re allowed to disagree.
A seller might say:
“There’s no way my house is only worth $390,000. We had three offers over $400,000.”
That information may be relevant, but disagreement alone doesn’t change the appraisal.
If there is legitimate information supporting a reconsideration of value, the appropriate ROV process may be available.
Otherwise, the buyer and seller need to decide whether they can restructure the transaction.
The seller can reduce the price.
The buyer can potentially contribute additional funds.
The parties can compromise.
Or, depending on the contract, the transaction may not continue.
What Happens If the Buyer Disagrees With the Inspection?
This sounds strange, but it happens.
An inspector might identify something that the buyer believes isn’t serious.
That’s okay.
The inspector provides information and professional observations.
The buyer then decides how that information affects their willingness to purchase the property.
You don’t have to demand that the seller repair every item in an inspection report.
In fact, treating an inspection as a giant seller repair list can sometimes make negotiations unnecessarily difficult.
The goal is to understand what matters.
Should You Ask the Seller to Fix Everything?
Probably not in most transactions.
Imagine buying a 30-year-old home.
The inspection identifies:
- A loose doorknob
- Minor cracked caulk
- A missing outlet cover
- An older furnace
- A leaking plumbing connection
- Significant roof deterioration
Those six items shouldn’t necessarily receive equal attention.
The roof and plumbing issue may matter considerably more than the doorknob.
The furnace age may be something you need to budget for even though it’s currently functioning.
The small cosmetic and maintenance items may simply become part of owning the home.
Good inspection negotiations tend to focus on meaningful concerns rather than trying to make an existing house brand new.
Should You Ask for Repairs or a Price Reduction?
It depends on what you’re trying to accomplish.
A repair solves the physical problem before closing.
A price reduction lowers what you’re paying for the property.
A seller concession, when permitted and properly structured, may help reduce eligible closing costs.
Those aren’t economically identical.
Suppose the house needs a $10,000 roof.
A $10,000 reduction in purchase price doesn’t put $10,000 into your checking account after closing.
If you’re financing most of the purchase, the monthly-payment reduction resulting from a $10,000 lower price may be relatively modest.
Meanwhile, you could still need $10,000 shortly after closing to replace the roof.
That’s why the structure of an inspection negotiation matters.
Real-World Scenario: Great Appraisal, Bad Inspection
Let’s put everything together.
You buy a home for:
$375,000
The appraisal comes back:
$380,000
Great news.
Then the inspection discovers significant foundation movement that requires further evaluation.
The high appraisal doesn’t make the foundation concern disappear.
Now the buyer needs to determine:
- How serious is the issue?
- What does a specialist say?
- What might repairs cost?
- Will the seller address it?
- Does it affect the mortgage?
- Does the buyer still want the property?
This is the perfect example of why appraisal and inspection aren’t substitutes.
Real-World Scenario: Great Inspection, Bad Appraisal
Now reverse it.
Purchase price: $375,000
The inspector says the home is in excellent condition.
Then:
Appraised value: $350,000
The condition isn’t the problem.
The valuation is.
Now the conversation becomes:
- Will the seller reduce the price?
- Can the buyer cover a gap?
- Is an ROV appropriate?
- Can the financing be restructured?
- What protections exist in the purchase agreement?
Again, completely different problem.
Real-World Scenario: FHA Repair Requirement
A first-time buyer is purchasing an older Michigan home using an FHA loan.
The home inspection doesn’t uncover anything that causes the buyer to walk away.
But the FHA appraisal identifies defective paint on an applicable pre-1978 structure.
The appraisal value supports the purchase price, but the required condition still needs to be addressed before the loan can proceed.
This isn’t a low-appraisal problem.
It’s a property eligibility issue.
Once the required repair is properly completed and documented, the transaction may be able to continue.
Real-World Scenario: Appraisal Waiver but Major Inspection Problem
A Conventional buyer receives an appraisal waiver.
Everyone is excited.
No traditional appraisal fee.
One less step.
Potentially faster mortgage process.
Then the buyer’s inspection identifies significant water intrusion in the basement.
The appraisal waiver did absolutely nothing to protect the buyer from that issue.
Why?
Because it was never designed to.
This may be the clearest example of the difference between the two services.
Common Appraisal and Inspection Mistakes Michigan Buyers Make
After helping buyers through mortgage transactions for years, many of the same misunderstandings come up repeatedly.
Mistake #1: Thinking the appraisal is a home inspection
It’s not.
Mistake #2: Thinking an FHA or VA appraisal replaces an inspection
It doesn’t.
Mistake #3: Assuming a low appraisal means you automatically need the entire difference in additional cash
The actual impact depends on the loan structure.
Mistake #4: Assuming a high appraisal eliminates property risk
A valuable house can still have expensive problems.
Mistake #5: Making a large appraisal-gap guarantee without reviewing the financing
Know exactly what the additional cash requirement could do to your loan and reserves.
Mistake #6: Waiving an inspection because the lender is ordering an appraisal
These serve completely different purposes.
Mistake #7: Panicking over every line of the inspection report
Focus on significance, not page count.
Mistake #8: Assuming seller concessions are the same as cash for repairs
They aren’t.
Mistake #9: Making financial changes to the purchase agreement without telling your mortgage company
Those changes may affect underwriting, disclosures or cash to close.
Mistake #10: Waiting until the appraisal is complete to discuss a property that obviously needs substantial repairs
If you’re buying a fixer-upper, talk about financing before the appraisal becomes the problem.
Frequently Asked Questions About Appraisals and Home Inspections
Is an appraisal the same as a home inspection?
No.
An appraisal primarily determines the property’s value for the mortgage transaction and addresses applicable property requirements.
A home inspection is designed to help the buyer understand the physical condition of the property.
Do I need both an appraisal and a home inspection?
You may.
Your mortgage may require an appraisal unless an eligible alternative such as an appraisal waiver applies.
A traditional home inspection is generally a separate decision made by the buyer.
One doesn’t replace the other.
Does the lender require a home inspection?
Generally, a standard buyer home inspection isn’t automatically required simply because you’re getting a mortgage.
However, particular properties, loan programs or circumstances can require additional inspections, testing or documentation.
Does FHA require a home inspection?
FHA requires an FHA appraisal for applicable transactions, but buyers shouldn’t confuse that with a comprehensive home inspection.
An FHA appraisal does not replace a buyer’s independent home inspection.
Does VA require a home inspection?
A VA appraisal isn’t the same as a home inspection.
VA has Minimum Property Requirements that are considered through the VA appraisal process, but Veterans may still choose to obtain a separate home inspection to better understand the property’s condition.
Can a house pass an appraisal and fail an inspection?
People often use the word “fail,” but yes—a property can have an acceptable appraisal while a home inspection uncovers significant defects.
The appraisal and inspection are evaluating different things.
Can a house have a good inspection and a low appraisal?
Absolutely.
A home can be in excellent physical condition but still not support the agreed-upon purchase price based on the appraisal analysis.
What happens if the appraisal is lower than my offer?
Your options may include renegotiating the purchase price, contributing additional funds, restructuring the financing, pursuing a reconsideration of value when appropriate or exercising applicable contractual rights.
The exact options depend on the mortgage and purchase agreement.
Can I challenge a low appraisal?
There may be an opportunity to request a Reconsideration of Value when there is legitimate information supporting review.
That could include relevant comparable sales, factual property errors or other material valuation information.
An ROV isn’t simply a request to increase the value because the transaction needs a higher number.
Can I get another appraisal if I don’t like the first one?
You generally can’t simply order appraisals repeatedly until one supports the desired value.
Appraisal independence requirements and loan-program rules apply.
There are situations where another appraisal may be appropriate, but there needs to be a legitimate basis.
Who chooses the appraiser?
Mortgage appraisal ordering is subject to appraisal independence requirements.
The buyer, seller, real estate agent and loan officer generally don’t simply choose a particular appraiser because they believe that person will provide the value they want.
Who chooses the home inspector?
The buyer generally selects the home inspector.
Your real estate agent may provide information or recommendations, but buyers should be comfortable with the professional they hire.
Should I get an inspection on a brand-new home?
New construction can still have defects or incomplete work.
Some buyers choose to have new homes professionally inspected even when builder warranties apply.
Should I get an inspection if I receive an appraisal waiver?
An appraisal waiver doesn’t evaluate the physical condition of the home.
Whether you obtain an inspection is a separate decision.
Does an appraisal waiver mean the lender thinks I’m getting a good deal?
Not necessarily.
An appraisal waiver means the transaction met applicable eligibility requirements to proceed without a traditional appraisal.
It shouldn’t be interpreted as the lender guaranteeing that you’re purchasing the property below market value.
Can an appraisal hurt my mortgage approval?
It can affect the transaction.
A low value may change the LTV and financing structure.
Property-condition issues may need to be addressed.
Other appraisal findings may require additional review.
That’s why the appraisal is an important part of mortgage underwriting.
Can an inspection hurt my mortgage approval?
The inspection report itself generally isn’t the same thing as the lender’s appraisal.
However, issues discovered through the inspection can lead to repairs, contract amendments, concessions or other circumstances that may affect the mortgage transaction.
Does the seller have to make repairs found during the inspection?
That depends on the purchase agreement, negotiations and circumstances.
The inspection report itself doesn’t automatically force the seller to repair everything the inspector identifies.
Does the seller have to make repairs required by the appraiser?
If a repair is required for the property to be eligible for the mortgage, someone generally needs to resolve the condition appropriately before that loan can close.
Whether the seller agrees to do so is a separate contractual and negotiation issue.
Can I finance repairs into my mortgage?
Certain renovation mortgage programs may allow eligible repairs or improvements to be incorporated into the financing.
For example, FHA 203(k) renovation financing may be worth evaluating for certain properties that need work.
A renovation loan is different from a standard mortgage and should be considered early in the transaction.
Appraisal or Inspection: Which One Matters More?
This is almost a trick question.
They’re measuring different things.
If I’m lending hundreds of thousands of dollars secured by a property, value matters.
If I’m the person who is about to own, live in and maintain that property, condition matters.
As the buyer, you care about both.
You want to know:
Am I paying a price the property can reasonably support?
and:
Do I understand what I’m actually buying?
The appraisal helps with the first question.
The inspection helps with the second.
Neither one can completely answer both.
The Best Time to Understand This Is Before You Make an Offer
A lot of mortgage problems are easier to solve when they’re discussed early.
If you’re considering an older home, tell us.
If the property needs significant work, tell us.
If you’re planning an appraisal-gap guarantee, let’s run the numbers first.
If you’re considering waiving an appraisal or inspection contingency, make sure you understand what that means.
If you’re using FHA or VA financing, understand the property requirements before assuming every house will work with every loan.
And if you’re unsure whether FHA or Conventional financing makes more sense for the property you’re considering, that’s something we can evaluate before you’re under pressure to close.
That’s the benefit of getting properly pre-approved before you start making offers.
A good pre-approval isn’t just about producing a letter.
It’s about having a mortgage strategy.
Buying a Home in Michigan? Know What You’re Paying For—and What You’re Buying
When you’re purchasing a home, it’s easy to become focused on the mortgage.
What’s the rate?
What’s the payment?
How much do I need down?
What are my closing costs?
Those things absolutely matter.
But the house matters too.
The mortgage tells us whether we can finance the property.
The appraisal helps us evaluate the property’s value for that financing.
The inspection helps you better understand its physical condition.
And underwriting ultimately brings the financial and property pieces together before the mortgage can close.
At BrightSide Lending, our job is to help Michigan homebuyers understand how all of those pieces interact—not simply quote an interest rate and hope everything works out.
Whether you’re buying in Macomb County, Oakland County or anywhere else in Michigan, we’ll help you evaluate your mortgage options, understand the process and identify potential financing issues as early as possible.
If you’re getting ready to buy a home, start with the mortgage pre-approval before you start making offers.
Then when you find the right house, you’ll already understand the financing side—and you’ll know exactly why the appraisal and home inspection are two very different pieces of the homebuying puzzle.
BrightSide Lending
307 East Street
Rochester, MI 48307
Appraisal vs. Home Inspection: Cost, Timing and What Michigan Buyers Should Expect
By now, the biggest distinction should be clear:
An appraisal helps answer whether the property’s value and condition support the mortgage.
A home inspection helps you understand the condition of the home you’re buying.
Both can uncover problems.
Both can affect a real estate transaction.
But they’re performed for different reasons, by different professionals, and the results can have very different consequences.
Let’s finish by looking at how these pieces fit together from accepted offer through closing—and answer some of the questions Michigan homebuyers ask most often.
How Much Does a Home Appraisal Cost in Michigan?
There isn’t one universal appraisal fee.
The cost can vary depending on factors such as:
- Property type
- Location
- Complexity
- Size
- Loan program
- Required appraisal product
- Availability of qualified appraisers
- Whether additional inspections or services are necessary
A typical single-family home appraisal may cost several hundred dollars, but unusual or complex properties can cost more.
Rather than focusing on an advertised appraisal price from somewhere online, look at the appraisal fee disclosed for your specific mortgage transaction.
The appraisal charge is one of the costs you’ll generally see when reviewing your Loan Estimate.
And remember: an appraisal fee and a home inspection fee are two separate expenses.
How Much Does a Home Inspection Cost in Michigan?
Home inspection pricing also varies.
Factors can include:
- Size of the house
- Age of the property
- Location
- Type of home
- Inspector
- Services included
Additional services can increase the total cost.
For example, you may choose to add:
- Radon testing
- Sewer scope
- Mold evaluation
- Well testing
- Septic evaluation
- Pest inspection
- Other specialized services
A buyer may look at the inspection price and think:
“That’s a lot of money for a house I don’t even own yet.”
That’s understandable.
But you’re about to potentially spend hundreds of thousands of dollars on the property.
Learning as much as reasonably possible about its condition before closing can provide valuable information for that decision.
When Do You Pay for the Appraisal?
The appraisal fee may be collected before the appraisal is performed or otherwise handled through the mortgage process.
This is one reason buyers can have expenses before closing.
Not every dollar associated with buying a home waits until the day you receive the keys.
Depending on the transaction, you may have already paid for things such as:
- Earnest money deposit
- Home inspection
- Appraisal
- Specialized inspections or testing
Then you’ll have the remaining applicable down payment, closing costs and prepaid expenses due through the closing.
This is why I don’t like reducing the homebuying conversation to:
“How much is my down payment?”
The better question is:
“How much money should I realistically have available for the entire transaction?”
When Do You Pay for the Home Inspection?
Home inspectors are generally paid directly by the buyer according to the inspector’s payment terms.
That often occurs around the time the inspection is performed.
The inspection fee usually isn’t something you’re financing into your standard mortgage just because it’s related to buying the house.
So when budgeting for a purchase, buyers should have some accessible funds available for expenses that can occur before closing.
How Long Does an Appraisal Take?
There isn’t a universal turnaround time.
The timeline can depend on:
- Appraiser availability
- Property location
- Property complexity
- Market conditions
- Loan program
- Access to the property
- Availability of comparable sales
- Whether additional information is needed
The appraisal process involves more than the appraiser walking through the house.
The appraiser also needs to complete the valuation analysis and appraisal report.
Once the report is received, it may also need to go through lender or underwriting review.
That’s why:
“The appraiser was at the house yesterday”
doesn’t necessarily mean:
“The appraisal is completely cleared today.”
How Long Does a Home Inspection Take?
The actual inspection may take several hours depending on the size, age and complexity of the property.
That’s one major difference from an appraisal.
The inspector may spend considerable time evaluating accessible components of the home, documenting findings and preparing a detailed report.
Buyers should ask the inspector when they can expect the completed report because inspection contingencies often operate within specific contractual timelines.
You don’t want to discover that you had three days to address an inspection issue after waiting four days to review the report.
Your real estate agent should help you keep track of the deadlines contained in your purchase agreement.
Who Gets the Appraisal Report?
Because the appraisal is obtained as part of the mortgage process, borrowers generally receive a copy of the appraisal or valuation information as required by applicable rules.
That doesn’t mean you should only look at the final value.
Read the report.
You may see:
- Subject property information
- Comparable sales
- Adjustments
- Property photographs
- Market information
- Property-condition comments
- Appraiser observations
- Final opinion of value
You don’t need to become an appraiser to understand the report.
But it’s worth knowing how the appraiser arrived at the value.
Who Gets the Home Inspection Report?
The home inspection is generally obtained by the buyer, and the report belongs within that inspection relationship subject to the inspector’s agreement and applicable circumstances.
This is important because the inspection report isn’t automatically the lender’s appraisal report.
Buyers sometimes assume every document generated during the purchase gets sent directly to the mortgage underwriter.
That’s not necessarily the case.
However, as we discussed earlier, issues discovered during an inspection can sometimes lead to contract changes, repairs or other circumstances that become relevant to the mortgage.
Does the Mortgage Company Need My Home Inspection Report?
Not normally simply because you chose to have the home inspected.
The lender has its own appraisal and underwriting requirements.
But don’t interpret that as:
“I should hide serious property issues from the lender.”
If the inspection results lead to amendments, repairs, credits, concessions or other changes to the transaction, those changes may need to be disclosed and reviewed.
The mortgage needs to reflect the actual transaction taking place.
Can You Use an Appraisal From Another Lender?
Sometimes borrowers switch lenders after an appraisal has already been completed and ask:
“Can’t you just use the appraisal I already paid for?”
The answer depends on the loan program, appraisal circumstances and applicable transfer requirements.
There are situations where an appraisal may potentially be transferred or used by another lender, and other situations where a new appraisal may be necessary.
So don’t assume either way.
If you’re considering changing lenders after the appraisal has been completed, ask the new mortgage company to review the situation before making the switch.
Can You Use an Old Home Inspection?
That’s really a different question.
Suppose the seller had an inspection performed six months ago and gives you the report.
Is that useful?
Sure.
Would I automatically treat it as equivalent to an inspection performed specifically for you today?
I wouldn’t.
The condition of a property can change.
The previous inspection may have had a different scope.
You may not have the same contractual relationship with that inspector.
Repairs may have been made—or problems may have developed—since the report was completed.
A previous report can provide information.
Whether it’s enough information for you to rely on when purchasing the property is a separate decision.
What Happens to the Appraisal If the Deal Falls Apart?
Generally, you’ve paid for a professional service that has already been performed.
If the purchase transaction falls apart afterward, you shouldn’t assume the appraisal fee will automatically be refunded.
The same basic concept applies to the home inspection.
You paid the inspector to inspect the property and provide information.
If you decide not to buy the house because of what the inspector discovered, the inspection may have done exactly what you hired the inspector to do.
You spent several hundred dollars to potentially avoid making a much more expensive mistake.
That’s not necessarily money wasted.
Can the Next Buyer Use Your Inspection?
Don’t assume your private inspection simply becomes the next buyer’s inspection.
Inspection reports, agreements and reliance rights can involve the inspector’s contractual terms.
The next buyer may decide to obtain their own inspection.
And from that buyer’s perspective, that may be the smarter choice.
When you’re making a purchase this large, relying exclusively on someone else’s old report to save a few hundred dollars can create unnecessary risk.
Can the Seller See the Appraisal?
This can depend on how information is shared during the transaction.
If an appraisal comes in low and the buyer wants the seller to reduce the purchase price, information from the appraisal may naturally become relevant to negotiations.
But the seller doesn’t control the appraisal simply because they own the property.
The appraisal was obtained in connection with the buyer’s mortgage transaction.
Your real estate agent can help determine what information should be shared during negotiations.
What Happens If the Seller Disagrees With the Appraisal?
They’re allowed to disagree.
A seller might say:
“There’s no way my house is only worth $390,000. We had three offers over $400,000.”
That information may be relevant, but disagreement alone doesn’t change the appraisal.
If there is legitimate information supporting a reconsideration of value, the appropriate ROV process may be available.
Otherwise, the buyer and seller need to decide whether they can restructure the transaction.
The seller can reduce the price.
The buyer can potentially contribute additional funds.
The parties can compromise.
Or, depending on the contract, the transaction may not continue.
What Happens If the Buyer Disagrees With the Inspection?
This sounds strange, but it happens.
An inspector might identify something that the buyer believes isn’t serious.
That’s okay.
The inspector provides information and professional observations.
The buyer then decides how that information affects their willingness to purchase the property.
You don’t have to demand that the seller repair every item in an inspection report.
In fact, treating an inspection as a giant seller repair list can sometimes make negotiations unnecessarily difficult.
The goal is to understand what matters.
Should You Ask the Seller to Fix Everything?
Probably not in most transactions.
Imagine buying a 30-year-old home.
The inspection identifies:
- A loose doorknob
- Minor cracked caulk
- A missing outlet cover
- An older furnace
- A leaking plumbing connection
- Significant roof deterioration
Those six items shouldn’t necessarily receive equal attention.
The roof and plumbing issue may matter considerably more than the doorknob.
The furnace age may be something you need to budget for even though it’s currently functioning.
The small cosmetic and maintenance items may simply become part of owning the home.
Good inspection negotiations tend to focus on meaningful concerns rather than trying to make an existing house brand new.
Should You Ask for Repairs or a Price Reduction?
It depends on what you’re trying to accomplish.
A repair solves the physical problem before closing.
A price reduction lowers what you’re paying for the property.
A seller concession, when permitted and properly structured, may help reduce eligible closing costs.
Those aren’t economically identical.
Suppose the house needs a $10,000 roof.
A $10,000 reduction in purchase price doesn’t put $10,000 into your checking account after closing.
If you’re financing most of the purchase, the monthly-payment reduction resulting from a $10,000 lower price may be relatively modest.
Meanwhile, you could still need $10,000 shortly after closing to replace the roof.
That’s why the structure of an inspection negotiation matters.
Real-World Scenario: Great Appraisal, Bad Inspection
Let’s put everything together.
You buy a home for:
$375,000
The appraisal comes back:
$380,000
Great news.
Then the inspection discovers significant foundation movement that requires further evaluation.
The high appraisal doesn’t make the foundation concern disappear.
Now the buyer needs to determine:
- How serious is the issue?
- What does a specialist say?
- What might repairs cost?
- Will the seller address it?
- Does it affect the mortgage?
- Does the buyer still want the property?
This is the perfect example of why appraisal and inspection aren’t substitutes.
Real-World Scenario: Great Inspection, Bad Appraisal
Now reverse it.
Purchase price: $375,000
The inspector says the home is in excellent condition.
Then:
Appraised value: $350,000
The condition isn’t the problem.
The valuation is.
Now the conversation becomes:
- Will the seller reduce the price?
- Can the buyer cover a gap?
- Is an ROV appropriate?
- Can the financing be restructured?
- What protections exist in the purchase agreement?
Again, completely different problem.
Real-World Scenario: FHA Repair Requirement
A first-time buyer is purchasing an older Michigan home using an FHA loan.
The home inspection doesn’t uncover anything that causes the buyer to walk away.
But the FHA appraisal identifies defective paint on an applicable pre-1978 structure.
The appraisal value supports the purchase price, but the required condition still needs to be addressed before the loan can proceed.
This isn’t a low-appraisal problem.
It’s a property eligibility issue.
Once the required repair is properly completed and documented, the transaction may be able to continue.
Real-World Scenario: Appraisal Waiver but Major Inspection Problem
A Conventional buyer receives an appraisal waiver.
Everyone is excited.
No traditional appraisal fee.
One less step.
Potentially faster mortgage process.
Then the buyer’s inspection identifies significant water intrusion in the basement.
The appraisal waiver did absolutely nothing to protect the buyer from that issue.
Why?
Because it was never designed to.
This may be the clearest example of the difference between the two services.
Common Appraisal and Inspection Mistakes Michigan Buyers Make
After helping buyers through mortgage transactions for years, many of the same misunderstandings come up repeatedly.
Mistake #1: Thinking the appraisal is a home inspection
It’s not.
Mistake #2: Thinking an FHA or VA appraisal replaces an inspection
It doesn’t.
Mistake #3: Assuming a low appraisal means you automatically need the entire difference in additional cash
The actual impact depends on the loan structure.
Mistake #4: Assuming a high appraisal eliminates property risk
A valuable house can still have expensive problems.
Mistake #5: Making a large appraisal-gap guarantee without reviewing the financing
Know exactly what the additional cash requirement could do to your loan and reserves.
Mistake #6: Waiving an inspection because the lender is ordering an appraisal
These serve completely different purposes.
Mistake #7: Panicking over every line of the inspection report
Focus on significance, not page count.
Mistake #8: Assuming seller concessions are the same as cash for repairs
They aren’t.
Mistake #9: Making financial changes to the purchase agreement without telling your mortgage company
Those changes may affect underwriting, disclosures or cash to close.
Mistake #10: Waiting until the appraisal is complete to discuss a property that obviously needs substantial repairs
If you’re buying a fixer-upper, talk about financing before the appraisal becomes the problem.
Frequently Asked Questions About Appraisals and Home Inspections
Is an appraisal the same as a home inspection?
No.
An appraisal primarily determines the property’s value for the mortgage transaction and addresses applicable property requirements.
A home inspection is designed to help the buyer understand the physical condition of the property.
Do I need both an appraisal and a home inspection?
You may.
Your mortgage may require an appraisal unless an eligible alternative such as an appraisal waiver applies.
A traditional home inspection is generally a separate decision made by the buyer.
One doesn’t replace the other.
Does the lender require a home inspection?
Generally, a standard buyer home inspection isn’t automatically required simply because you’re getting a mortgage.
However, particular properties, loan programs or circumstances can require additional inspections, testing or documentation.
Does FHA require a home inspection?
FHA requires an FHA appraisal for applicable transactions, but buyers shouldn’t confuse that with a comprehensive home inspection.
An FHA appraisal does not replace a buyer’s independent home inspection.
Does VA require a home inspection?
A VA appraisal isn’t the same as a home inspection.
VA has Minimum Property Requirements that are considered through the VA appraisal process, but Veterans may still choose to obtain a separate home inspection to better understand the property’s condition.
Can a house pass an appraisal and fail an inspection?
People often use the word “fail,” but yes—a property can have an acceptable appraisal while a home inspection uncovers significant defects.
The appraisal and inspection are evaluating different things.
Can a house have a good inspection and a low appraisal?
Absolutely.
A home can be in excellent physical condition but still not support the agreed-upon purchase price based on the appraisal analysis.
What happens if the appraisal is lower than my offer?
Your options may include renegotiating the purchase price, contributing additional funds, restructuring the financing, pursuing a reconsideration of value when appropriate or exercising applicable contractual rights.
The exact options depend on the mortgage and purchase agreement.
Can I challenge a low appraisal?
There may be an opportunity to request a Reconsideration of Value when there is legitimate information supporting review.
That could include relevant comparable sales, factual property errors or other material valuation information.
An ROV isn’t simply a request to increase the value because the transaction needs a higher number.
Can I get another appraisal if I don’t like the first one?
You generally can’t simply order appraisals repeatedly until one supports the desired value.
Appraisal independence requirements and loan-program rules apply.
There are situations where another appraisal may be appropriate, but there needs to be a legitimate basis.
Who chooses the appraiser?
Mortgage appraisal ordering is subject to appraisal independence requirements.
The buyer, seller, real estate agent and loan officer generally don’t simply choose a particular appraiser because they believe that person will provide the value they want.
Who chooses the home inspector?
The buyer generally selects the home inspector.
Your real estate agent may provide information or recommendations, but buyers should be comfortable with the professional they hire.
Should I get an inspection on a brand-new home?
New construction can still have defects or incomplete work.
Some buyers choose to have new homes professionally inspected even when builder warranties apply.
Should I get an inspection if I receive an appraisal waiver?
An appraisal waiver doesn’t evaluate the physical condition of the home.
Whether you obtain an inspection is a separate decision.
Does an appraisal waiver mean the lender thinks I’m getting a good deal?
Not necessarily.
An appraisal waiver means the transaction met applicable eligibility requirements to proceed without a traditional appraisal.
It shouldn’t be interpreted as the lender guaranteeing that you’re purchasing the property below market value.
Can an appraisal hurt my mortgage approval?
It can affect the transaction.
A low value may change the LTV and financing structure.
Property-condition issues may need to be addressed.
Other appraisal findings may require additional review.
That’s why the appraisal is an important part of mortgage underwriting.
Can an inspection hurt my mortgage approval?
The inspection report itself generally isn’t the same thing as the lender’s appraisal.
However, issues discovered through the inspection can lead to repairs, contract amendments, concessions or other circumstances that may affect the mortgage transaction.
Does the seller have to make repairs found during the inspection?
That depends on the purchase agreement, negotiations and circumstances.
The inspection report itself doesn’t automatically force the seller to repair everything the inspector identifies.
Does the seller have to make repairs required by the appraiser?
If a repair is required for the property to be eligible for the mortgage, someone generally needs to resolve the condition appropriately before that loan can close.
Whether the seller agrees to do so is a separate contractual and negotiation issue.
Can I finance repairs into my mortgage?
Certain renovation mortgage programs may allow eligible repairs or improvements to be incorporated into the financing.
For example, FHA 203(k) renovation financing may be worth evaluating for certain properties that need work.
A renovation loan is different from a standard mortgage and should be considered early in the transaction.
Appraisal or Inspection: Which One Matters More?
This is almost a trick question.
They’re measuring different things.
If I’m lending hundreds of thousands of dollars secured by a property, value matters.
If I’m the person who is about to own, live in and maintain that property, condition matters.
As the buyer, you care about both.
You want to know:
Am I paying a price the property can reasonably support?
and:
Do I understand what I’m actually buying?
The appraisal helps with the first question.
The inspection helps with the second.
Neither one can completely answer both.
The Best Time to Understand This Is Before You Make an Offer
A lot of mortgage problems are easier to solve when they’re discussed early.
If you’re considering an older home, tell us.
If the property needs significant work, tell us.
If you’re planning an appraisal-gap guarantee, let’s run the numbers first.
If you’re considering waiving an appraisal or inspection contingency, make sure you understand what that means.
If you’re using FHA or VA financing, understand the property requirements before assuming every house will work with every loan.
And if you’re unsure whether FHA or Conventional financing makes more sense for the property you’re considering, that’s something we can evaluate before you’re under pressure to close.
That’s the benefit of getting properly pre-approved before you start making offers.
A good pre-approval isn’t just about producing a letter.
It’s about having a mortgage strategy.
Buying a Home in Michigan? Know What You’re Paying For—and What You’re Buying
When you’re purchasing a home, it’s easy to become focused on the mortgage.
What’s the rate?
What’s the payment?
How much do I need down?
What are my closing costs?
Those things absolutely matter.
But the house matters too.
The mortgage tells us whether we can finance the property.
The appraisal helps us evaluate the property’s value for that financing.
The inspection helps you better understand its physical condition.
And underwriting ultimately brings the financial and property pieces together before the mortgage can close.
At BrightSide Lending, our job is to help Michigan homebuyers understand how all of those pieces interact—not simply quote an interest rate and hope everything works out.
Whether you’re buying in Macomb County, Oakland County or anywhere else in Michigan, we’ll help you evaluate your mortgage options, understand the process and identify potential financing issues as early as possible.
If you’re getting ready to buy a home, start with the mortgage pre-approval before you start making offers.
Then when you find the right house, you’ll already understand the financing side—and you’ll know exactly why the appraisal and home inspection are two very different pieces of the homebuying puzzle.
BrightSide Lending
307 East Street
Rochester, MI 48307
People. Solutions. A Brighter Tomorrow.
People. Solutions. A Brighter Tomorrow.


